Author: Blue Sky
Budgeting for French Property: How Much Are Service Charges (Charges de Copropriété)?
Buyers budget carefully for the purchase price, the notaire’s fees and the mortgage. Service charges are frequently an afterthought — and then arrive as a quarterly demand that materially changes the economics of ownership.
If you are buying an apartment in France, you are buying into a copropriété: a legal community of owners collectively responsible for the building. Your share of running it is not optional, it is not negotiable after purchase, and over a ten-year hold it can easily exceed the notaire’s fees several times over.
Here is what to expect and, more importantly, what to check before you commit.
The numbers
Charges are quoted per square metre per year, which makes comparison across properties straightforward once you know the benchmarks.
In the Île-de-France region the average sits at roughly €43 per square metre per year, with Paris higher at around €46. Elsewhere: Nice around €37, Bordeaux €33, Lille €30, Marseille and Strasbourg €29, Montpellier €27, Lyon and Toulouse €26, Nantes €25. Simpler provincial buildings with limited communal facilities commonly fall in the €20 to €30 range.
Applied to a typical 70m² apartment, that is roughly €1,750 a year in Lyon, €3,000 in Île-de-France and something above €3,200 in central Paris — before taxe foncière, before taxe d’habitation on a second home, and before insurance on your own lot.
The trajectory is worth noting too. Charges in the Paris region rose by close to 11% over the 2023 to 2025 period, well ahead of general inflation, driven principally by energy costs and by the accelerating programme of building renovation works.
What you are actually paying for
Charges divide into distinct categories, and the distinction affects who pays what.
Charges générales cover the running of the building as a whole — the syndic‘s management fee, the general meeting, building insurance, common-area maintenance, administration. Every owner contributes in proportion to their share.
Charges spéciales relate to specific services and equipment, and are allocated according to the objective benefit each lot derives. The lift is the classic example: ground-floor apartments typically pay a reduced share or none at all. Heating, hot water, the entryphone and the gardien fall into this category too.
Charges exceptionnelles are one-off levies for major works — façade renovation, roof replacement, lift modernisation, energy retrofits — voted at general meeting and called separately.
Across most buildings, energy is the largest and fastest-growing line, particularly where there is collective heating. Staffing is next: a resident gardien provides real amenity but is a substantial fixed cost. Management fees run in the region of €150 to €200 per lot per year, typically 10% to 12% of routine charges.
How your share is calculated
Your contribution is fixed by the tantièmes — sometimes millièmes — set out in the building’s règlement de copropriété. These are shares of the whole, allocated principally on the surface area, position and character of each lot.
Two things follow. First, the allocation is a matter of record, not negotiation: you can and should ask for your exact tantièmes before you buy. Second, a large apartment in a small building carries a large share of every collective decision — including expensive ones.
The règlement also defines what is common and what is private, which becomes important the moment anything needs repairing.
The fund you may not have budgeted for
Since the loi ALUR, most copropriétés must maintain a fonds de travaux — a compulsory reserve for future works, funded by an annual contribution of at least 5% of the building’s operating budget, and often more where a technical survey identifies significant needs.
Here is the part that catches buyers out: the fund stays with the building. Sums you have contributed are not refunded when you sell. They belong to the copropriété, not to you. Factor this into a short-hold investment case rather than treating it as recoverable capital.
The due diligence that actually matters
The seller must supply the copropriété documentation before you sign, and the ten-day cooling-off period exists partly so you can read it. Most buyers do not. These are the questions worth answering.
What have charges actually been? Ask for three years of accounts, not a single year’s figure. A sharp recent increase is informative.
What works have been voted? Read the minutes of the last three general meetings. Works approved before completion are typically payable by the party who owned the lot when the call for funds was issued — but this is contractual and must be settled explicitly in the deed. A voted but uncalled façade renovation can represent tens of thousands of euros.
What is the arrears position? A building where several owners are not paying is a building where the compliant owners eventually make up the shortfall.
What does the DPE and the building’s technical plan say? Energy retrofit obligations are tightening, and a poorly rated building carries a foreseeable capital demand.
Is there a gardien, a lift, a pool, collective heating? Each is a permanent cost line. A concierge and a heated pool are pleasant; they are also why one building charges €45 per square metre and the one next door charges €22.
What this means for your mortgage
Service charges are not a footnote to the financing — they are part of it. French lenders apply a debt-service ratio of around 35% of gross income, and recurring property costs form part of the affordability picture. For a rental investment, charges directly reduce the net yield the lender and you will both be assessing.
Buyers coming from markets where service charges are modest should recalibrate. A well-run French building with a lift, a gardien and collective heating is not cheap to run, and the charge reflects genuine service rather than inefficiency. The mistake is not paying it — it is failing to price it in.
Talk to BlueSky
BlueSky Finance builds the full cost of ownership into every mortgage recommendation — service charges, local taxes, insurance and loan insurance — so the figure you plan around is the real one rather than the headline monthly payment. If you are assessing an apartment purchase in France, contact our team for a clear view of what it will actually cost to own.
Legal Protections for Property Buyers in France: Cooling-off Periods, Conditions & Safeguards

Buyers arriving from the United Kingdom or the United States frequently ask us the same anxious question: what stops this going wrong?
In the UK, a seller can accept a higher offer days before exchange and the buyer’s costs simply evaporate. France works differently, and the difference is deliberate: French property law assumes the buyer is the weaker party and needs statutory protection, not merely contractual goodwill. The result is one of the most buyer-friendly conveyancing regimes in Europe. Here are the safeguards you are relying on, and how to use them properly.
1. The ten-day cooling-off period
Once you sign the preliminary contract — a compromis de vente or promesse de vente — you have ten calendar days in which to withdraw for any reason, or for no reason at all.
The clock starts the day after you receive the signed contract and its full annexes by registered post or secure electronic delivery. No penalty applies. No justification is required. Any deposit already lodged must be repaid in full within 21 days of your written notice.
This right belongs to the buyer alone — once the seller signs, they are committed. Crucially, the period does not begin until the complete file has been delivered, including the diagnostic reports and, for an apartment, the copropriété documentation. An incomplete delivery can leave the withdrawal period running long after you assumed it had closed. Use the ten days properly: read the diagnostics, read the last three years of copropriété minutes, and ask the questions you were too polite to ask before signing.
2. The mortgage condition
If you are borrowing, the preliminary contract must contain a condition suspensive d’obtention de prêt. This is a statutory protection, not a negotiated favour.
The contract must specify the loan amount, the maximum interest rate and the term. If financing on those terms is refused, the sale falls away and your deposit is returned in full without deduction. The law sets a minimum period of one month for obtaining the loan; in practice notaires typically allow 45 to 60 days, and for an international application you should push for the longer end.
Two points determine whether the protection actually works for you.
First, the figures in the clause must match the loan you will genuinely need. A clause drafted for a €400,000 loan at a maximum of 3.5% offers no protection if you subsequently need €450,000 at 4%. Have your broker check the wording before the contract is signed.
Second, you must pursue the application in good faith. A buyer who never applies, or who engineers a refusal, forfeits the protection and risks losing the deposit.
You may waive the loan condition — sellers sometimes push for it in competitive situations — but the waiver must be handwritten and signed. That formality exists because the consequence is severe: without the condition, a mortgage refusal leaves you liable. Take independent advice first. Note that a mortgage can be arranged after completion in France, so waiving the condition does not mean abandoning finance — but it does mean carrying the risk yourself.
3. The Scrivener reflection period on your loan offer
The protection continues into the financing itself.
When a French lender issues a formal offre de prêt, you are legally prohibited from accepting it before the eleventh day after receipt. The delay is compulsory and cannot be shortened, even at your own request. The offer must remain open for thirty days, giving you a genuine window to compare terms.
The offer must also set out, in prescribed form, the total cost of credit — the TAEG — including interest, arrangement fees, guarantee costs and mandatory insurance. And the loan is itself conditional: if the purchase does not complete within four months, the offer lapses. The delay frustrates buyers on a tight timetable, but the reason is sound. Build it into your schedule from the start.
4. The other conditions suspensives
Beyond the loan, a well-drafted contract suspends the sale on other matters: the commune’s right of pre-emption, which gives the local authority two months to decide whether to acquire the property itself; the absence of undisclosed servitudes; a clear mortgage register; the technical diagnostics; any planning permission you require; and occasionally the sale of your existing property. Each is a door out of the contract if the answer comes back wrong. Ask your notaire which apply and make sure they are drafted in.
5. The notaire
The role has no direct equivalent in the common-law world, and it is the backbone of the system.
A notaire is a public officer, not a partisan lawyer. They verify title, conduct the searches, confirm the seller’s capacity to sell, collect the transfer taxes, draft the deed and register it. The acte authentique they produce has evidential force that a private contract does not — which is why title insurance is unnecessary in France. Notaires hold funds in regulated escrow accounts and the profession is closely supervised. A single notaire may act for both parties, which is common and entirely proper; if you would prefer your own, you may appoint a second at no extra cost, as the fee is shared rather than doubled.
6. Full disclosure, by law
The seller cannot leave you to discover problems yourself. A dossier de diagnostic technique must be annexed to the contract, covering energy performance, asbestos, lead, termites, gas and electrical installations, and natural and technological risk exposure. For an apartment, the seller must also supply the copropriété’s financial position, recent meeting minutes and the schedule of forthcoming works. The energy rating deserves particular attention in 2026: F and G rated properties face progressive restrictions on letting, and many lenders now price them less favourably or require a renovation plan.
The honest caveat
These protections are strong, but not automatic. They depend on a contract correctly drafted for your circumstances, on deadlines properly diarised, and on you actually reading what you are given. Buyers who run into difficulty in France are almost never let down by the system — they are the ones who signed something they had not read, or waived a condition they did not understand. Slow down at the preliminary contract. Everything downstream depends on it.
Talk to BlueSky
BlueSky Finance works alongside your notaire and agent to make sure the mortgage condition in your contract reflects the loan you will actually need, and that the financing timetable fits the legal deadlines rather than fighting them. If you are approaching a preliminary contract, contact our team before you sign — that is when we can be most useful.
Can You Buy Property Alone in France If You’re Married? (Matrimonial Regimes Explained)

It is one of the most consequential questions in a French purchase, and one of the least anticipated: can I buy this property — and borrow against it — in my name alone?
The answer has almost nothing to do with the lender’s appetite and almost everything to do with your matrimonial regime. In France, the framework governing property between spouses is no background technicality: it determines who signs the deed, whose name goes on the loan, whose income the bank can count, and what happens to the asset on divorce or death. For international couples this is unfamiliar ground, because most common-law jurisdictions have no direct equivalent.
Why the notaire asks about your marriage first
France applies a matrimonial regime to every married couple — a body of rules determining which assets are individually owned and which are jointly owned. If you signed a marriage contract before a notaire, that contract sets the regime. If you did not, the law supplies one by default.
For couples married in France without a contract, the default is the communauté réduite aux acquêts. Assets owned before the marriage remain personal. Assets acquired during the marriage are, in principle, community property regardless of whose income paid for them.
For couples married abroad, the applicable regime is determined by international private law rules turning on where you were habitually resident and when you married. Your notaire will establish this early — and international couples are sometimes surprised by the answer.
Séparation de biens: the most straightforward position
Under séparation de biens, each spouse owns their assets independently. There is no community estate.
This is the cleanest position for a solo purchase. One spouse can buy in their sole name, borrow in their sole name, and hold the property as their own. Lenders assess that spouse’s income and liabilities on a standalone basis, without requiring the other to join the loan.
It suits a purchase funded from one spouse’s pre-marital wealth or inheritance, an investment intended for one family branch, or a case where one spouse’s income and debt profile supports the application and the other’s does not. The trade-off is that the non-owning spouse acquires no interest in the property — a point for the couple to consider together rather than a problem for the lender to solve.
Communauté: both names, usually
Under a community regime, a property purchased during the marriage generally belongs to the community regardless of who signs. Lenders reflect this reality: both spouses will normally be required to appear on the purchase contract and on the loan as co-borrowers, and both incomes and both sets of liabilities enter the affordability calculation.
That can be an advantage. Two incomes support more borrowing than one within the debt-service limits French lenders apply.
There is one narrow route to buying alone under a community regime, and it depends entirely on the source of the funds. Where the purchase is financed from a spouse’s genuinely personal money — an inheritance, a gift, or assets held before the marriage — the property can be treated as that spouse’s own. This requires a déclaration de remploi in the notarial deed, explicitly recording the origin of the funds and the intention that the asset remain personal. It must be done at the time of purchase. It cannot be retrofitted afterwards, and without it the presumption of community applies.
Under a communauté universelle, where essentially everything is pooled, a solo purchase is not realistically available without amending the regime itself.
The consent rules that catch people out
Two provisions of the Civil Code apply regardless of who is named on the deed, and both matter to a mortgage application.
Article 1415 governs borrowing under a community regime. A spouse who borrows alone commits only their own income and personal assets — not the community estate — unless the other spouse expressly consents. Lenders know this. It is why, under a community regime, a bank lending a substantial sum will normally want the other spouse either as co-borrower or as a consenting party, even where only one name appears on the title.
Article 215 protects the family home. Neither spouse can dispose of the property serving as the family residence, or the rights over it, without the other’s agreement — whatever the matrimonial regime says and whoever owns it. In practice this means that a French main residence cannot be sold or mortgaged unilaterally.
The result is worth stating plainly: under a community regime, buying alone is possible in the right circumstances, but borrowing alone in any meaningful amount usually is not.
Participation aux acquêts and PACS
Participation aux acquêts operates as separation of property during the marriage — each spouse buys and borrows independently — with a balancing settlement on dissolution. For purchasing purposes it behaves much like séparation de biens. Couples in a PACS are, under the default regime, treated as separate owners, with jointly purchased property held in indivision in the proportions stated in the deed. Set those proportions deliberately.
Regimes can be changed by notarial act, with judicial approval where minor children are involved and with costs and possible tax consequences. It is a legitimate planning step, but not one to attempt mid-transaction: if your regime is likely to obstruct the purchase, raise it with your notaire before you sign a preliminary contract, not after.
The practical sequence
Establish your regime with the notaire at the outset and share it with your broker before the mortgage application is prepared: it determines whose financial profile will be assessed. If a solo purchase under a community regime is the plan, make sure the déclaration de remploi is drafted into the deed. And be candid about the source of funds — the notaire must verify it in any case.
Get this right at the beginning and it is a formality. Get it wrong and it can unwind a transaction weeks before completion.
Talk to BlueSky
BlueSky Finance arranges mortgages for international couples across France, and we structure applications around your matrimonial position from the outset — whose income the lender can count, who needs to sign, and which banks are comfortable with your circumstances. Contact our team early in your search and we will make sure the financing and the ownership structure fit together.
Buying Property in France: How Much Security Deposit Is Required?

The moment an offer is accepted on a French property, the first cash call arrives. It is not the notaire’s fees and it is not the down payment on the mortgage. It is the séquestre — the security deposit lodged when the preliminary contract is signed.
Buyers arriving from other markets often find this stage unsettling. A significant sum leaves your account months before you own anything, and the legal vocabulary around it is unfamiliar. In practice, French law protects this money unusually well. Here is what to expect.
How much is required?
The market convention is 5% to 10% of the purchase price, most commonly 10% on a promesse de vente and 5% on a compromis de vente. On a €600,000 property that means €30,000 to €60,000 committed at signature.
There is one point that surprises almost everyone: no French law requires a deposit at all. Case law simply holds that it must be less than the sale price. The percentage is commercial custom, not statute — which has an important practical consequence, addressed below.
The deposit is not an additional cost. It is an advance on the purchase price and is credited in full at completion. On that €600,000 purchase with a €60,000 deposit, you transfer €540,000 plus fees on the day of signing the acte de vente.
Is it negotiable?
Yes — more often than buyers assume, because the deposit exists to serve the seller’s interests rather than to satisfy a legal requirement.
The seller is being asked to take the property off the market for two to three months while you arrange finance. The deposit is their compensation for that risk, and it is a proxy for how serious you are. Anything that reduces the seller’s perceived risk therefore strengthens your case for reducing the deposit.
In practice, three arguments carry weight. A mortgage pre-approval or accord de principe already in hand demonstrates that your financing condition is a formality rather than a gamble. A short, well-defined completion timetable limits the period the seller is exposed. And in a calmer local market, a seller with few competing offers has less leverage.
We regularly see deposits negotiated to 5% on a promesse, and occasionally to 2% or 3% on higher-value transactions or where the buyer’s file is exceptionally strong. It is always worth raising through the agent before the contract is drafted — not afterwards.
Non-resident buyers should flag their situation early: international transfers take time, and anti-money-laundering checks on funds arriving from outside the SEPA zone can add days.
Where does the money actually go?
Not to the seller. The deposit is held in escrow, and where it is held matters.
The safer route, and the one we recommend, is the notaire’s regulated escrow account. Notaires are public officers holding client funds in supervised accounts, and the money can only be released in accordance with the terms of the contract.
The alternative is escrow with the estate agent, who must hold a specific financial guarantee under the loi Hoguet. This is legitimate but less common on higher-value transactions, and it is entirely reasonable to insist on the notaire.
One security point deserves emphasis. Fraudsters routinely intercept email and substitute their own bank details for the notaire’s. Never wire funds on the strength of an emailed attachment alone. Telephone the notaire’s office on a number you have sourced independently and confirm the IBAN character by character before releasing anything.
When do you get it back?
This is where French law becomes genuinely protective of the buyer. There are three principal routes to recovering the deposit in full.
The cooling-off period. Every non-professional buyer has an unconditional right of withdrawal for ten calendar days after receiving the signed preliminary contract. No reason is required and no penalty applies. The deposit must be returned within 21 days of written notice of withdrawal.
Failure of a condition suspensive. The preliminary contract will contain suspensive conditions — most importantly the mortgage condition. If your loan application is properly pursued and refused within the agreed period, the contract falls away and the deposit is returned in full, without deduction, on the same 21-day timeline. Other conditions commonly cover the commune’s pre-emption right, planning searches, servitudes and the absence of undisclosed charges over the title.
Seller default. If the seller withdraws, you recover the deposit and may have a claim for damages besides.
The critical caveat: you must pursue the loan application in good faith. A buyer who fails to apply, or who deliberately submits an application designed to be refused, risks losing the protection of the condition.
Compromis or promesse — the difference matters
The two preliminary contracts allocate risk differently, and the deposit behaves differently under each.
A compromis de vente is a mutual undertaking: both parties commit to the sale, subject to the conditions. A promesse unilatérale de vente is a one-sided option — the seller commits, and you buy the right to decide. Under a promesse, the sum lodged is technically an indemnité d’immobilisation, typically 10%, and it compensates the seller for holding the property. If you walk away after the cooling-off period for a reason not covered by a suspensive condition, that sum is generally forfeit.
Under both contracts the ten-day withdrawal right and the protection of the suspensive conditions apply. The difference bites only when a buyer changes their mind for reasons the contract does not cover.
Before you sign
Read the mortgage condition twice. Check the amount, the rate ceiling and the maximum term it specifies — if you later need to borrow more, or for longer, than the clause permits, a refusal may not trigger your protection. Check the deadline, which by law must be at least one month and in practice should be 45 to 60 days. And never accept pressure to waive the loan condition without independent advice.
Talk to BlueSky
Blue Sky Finance helps international buyers arrive at the negotiating table with financing already in hand — which is frequently what makes a lower deposit and a tighter mortgage condition achievable. We can provide an early indication of borrowing capacity before you make an offer, and work with your notaire to make sure the suspensive conditions in your contract match the loan you will actually be arranging. Contact our team to get started.
French Mortgages for US Citizens: How They Compare to American Home Loans

American buyers routinely tell us they expected French financing to be broadly similar to a US home loan, only in a different language. It is not. The two systems were built on different assumptions about risk, and the differences show up in pricing, paperwork and process.
For the buyer, the headline is favourable: euro borrowing is currently considerably cheaper than dollar borrowing. The 30-year fixed rate in the United States has been sitting around 6.6%, with the 15-year near 6%. Fixed rates for international buyers in France run broadly between 3.5% and 4.5%, and for US-based applicants typically in the upper part of that band. That spread is the single most compelling reason for an American to finance rather than wire the full purchase price.
Here is how the rest compares.
Credit scores don’t travel — and don’t matter
There is no FICO equivalent in France. No French bank will pull your score, and an 800 credit rating buys you nothing at the credit committee.
What French lenders assess instead is documented income stability and the ratio of your total debt service to your gross income. Regulatory guidance caps that ratio at 35%, insurance premium included, with limited discretion for lenders to go beyond it. Note that this is generally applied to all your existing debt — US mortgage payments, auto loans, student loans — without netting off the rental income those assets may generate. Americans with several financed investment properties are sometimes surprised by how much borrowing capacity that consumes.
Expect to supply three years of federal tax returns, W-2s or audited business accounts, recent pay stubs, bank and brokerage statements, and a schedule of existing liabilities. A US credit report is often requested as supporting evidence, but as context rather than as a score.
Fixed means fixed — and there is no 30-year
Both markets favour fixed rates, but for different reasons and over different horizons.
The US 30-year fixed is a product of a specific securitisation market. France does not have that market, and terms are shorter: 20 to 25 years is the practical maximum, with amortisation generally required to complete by age 75 or 80. Against that, French fixed rates run for the entire term with no reset, no ARM structure and no reversion.
The offsetting difference is prepayment. In the US, most conventional mortgages carry no prepayment penalty at all. France permits one, but caps it: the lesser of six months’ interest on the amount repaid. It can frequently be negotiated away at the outset, and it is waived entirely in certain circumstances including sale after professional relocation, involuntary job loss or death.
Loan-to-value and the FATCA factor
American buyers should plan for a deposit of 25% to 40% of the purchase price, with 60% to 75% loan-to-value the working assumption. Minimum loan sizes typically start around €250,000 to €300,000.
Then there is FATCA. US reporting obligations mean that only a subset of French banks actively lend to US citizens and green card holders. This is not a credit judgement; it is a compliance decision, and it varies bank by bank and desk by desk. The practical consequence is that the panel of lenders available to an American buyer is narrower than the panel available to a British or German one — which makes knowing who is genuinely open for business a significant advantage.
No escrow, no title insurance, no closing agent
The American closing apparatus does not exist in France, and the substitutes work differently.
There is no monthly escrow account collecting property tax and homeowners’ insurance alongside your payment. In France you receive and pay the taxe foncière — and, on a second home, the taxe d’habitation — directly, once a year. Budget for them separately.
There is no title insurance either, because the notaire’s role removes the need for it. The notaire is a public officer who verifies title, conducts the searches, drafts the deed and registers the sale. Their fees, together with transfer taxes, come to roughly 7% to 7.5% of the price on an existing property, depending on the department, and materially less on a new build. Americans should treat this as the equivalent of closing costs and budget accordingly.
Insurance you must have, and a signature you must wait for
Two French requirements have no US parallel.
The first is assurance emprunteur — life and disability cover assigned to the loan. In practice it is mandatory, it is priced on age and medical history, and it can be a meaningful monthly cost for older borrowers. You are entitled to source it independently rather than accept the bank’s group policy, and doing so often saves a considerable sum over the term.
The second is the statutory reflection period. Once a French lender issues a formal loan offer, you are legally prohibited from accepting it before the eleventh day, and the offer must remain open to you for thirty days. The wait is not negotiable and it is not a delay tactic — it is a consumer protection, and it should be built into your closing timetable rather than discovered at the last minute.
And the tax question
Financing a French property has consequences on both sides of the Atlantic — French wealth tax on real estate, rental income treatment under the régime réel, foreign tax credits, currency gain on debt repayment, and reporting obligations including FBAR and Form 8938.
Talk to BlueSky
Blue Sky Finance arranges French mortgages for US citizens and green card holders, and works with the lenders who remain genuinely active in this segment. We know how to present an American financial profile to a French credit committee, and we coordinate with your notaire and cross-border accountant throughout. Contact our team to discuss your purchase.
French vs. UK Mortgages: 5 Critical Differences Every British Buyer Must Know

British buyers arrive in the French mortgage market carrying a set of assumptions built over decades of UK borrowing. Fix for two years. Remortgage before the reversion rate bites. Watch the early repayment charge. Repeat.
Almost none of that applies in France. The French mortgage market is built on a different philosophy — long-term certainty rather than short-term pricing — and once you understand the logic, it is a market that treats borrowers rather well. Here are the five differences that matter most.
1. You fix for the whole loan, not for two years
This is the fundamental divergence. In the UK, a fixed rate is a temporary product feature: two years, five at most, after which you fall onto a standard variable rate or arrange a new deal. Average UK two-year fixes at 75% loan-to-value are currently around 5.2%, five-year fixes around 5.3%, with standard variable rates well above 7% and the Bank of England base rate at 3.75%.
In France, “fixed” means fixed for the entire term. Take a twenty-year loan at 3.7% and you will pay 3.7% in year nineteen. There is no reversion rate, no product-transfer treadmill and no repricing risk. International buyers are currently seeing fixed rates broadly between 3.5% and 4.5% depending on residency, loan size and term.
For a second home or an investment property held for the long term, the value of that certainty is difficult to overstate. You know the euro cost of ownership on day one, for the life of the loan.
2. Nobody is looking at your credit score
The UK underwriting model leans heavily on credit reference data. France does not have a consumer credit scoring system in the British sense.
Instead, French lenders assess three things: the stability and documented provenance of your income, your debt-to-income ratio, and the quality of the asset. Expect to provide three years of tax returns, recent payslips or audited accounts if self-employed, bank statements and a full picture of existing borrowings. Expect the file to be read carefully by a human being.
The regulatory framework is explicit. National guidance caps total household debt service — including the mandatory loan insurance premium — at 35% of gross income, and generally limits terms to 25 years, with banks holding a limited discretionary margin outside those parameters. Critically, most French lenders apply this on an absolute basis rather than netting rental income against the mortgage it funds, which is why existing UK borrowings can constrain a French application more than British buyers expect.
3. You renegotiate; you don’t remortgage
British borrowers switch lenders as a matter of routine. In France, that is the expensive route. Refinancing means a new loan, a new guarantee, fresh notarial costs and a fresh set of fees.
The French practice is renégociation — going back to your existing lender and asking them to reduce the rate on the existing facility. If rates have fallen materially since you signed, and you have run the account well, banks will often oblige rather than lose the relationship. The costs are a fraction of a full refinance, and there is no need to re-run the entire underwriting process.
The practical implication for a UK buyer is that choosing a lender in France is more like choosing a bank than choosing a product. The relationship has a longer life.
4. Exit costs are capped by law
The UK early repayment charge is a contractual matter and can be punishing — commonly several per cent of the balance, tapering across the fixed period.
France caps it by statute. On a residential mortgage, any early repayment indemnity cannot exceed the lesser of six months’ interest on the capital repaid at the loan’s average rate, or 3% of the outstanding capital. No penalty at all is due where repayment follows a sale prompted by professional relocation, involuntary loss of employment, or death. And in practice these fees are frequently negotiated away entirely at the outset — which is one of the more valuable things a broker can secure for you.
French consumer law also gives you the right to overpay. Monthly instalments can typically be increased by 30% to 50%, subject to the contract terms, allowing you to shorten the loan without refinancing.
5. Loan insurance is mandatory — and switchable
Here is a cost line British buyers rarely budget for. French lenders require assurance emprunteur, a life and disability policy assigned to the loan. It is not optional in any meaningful sense, and for older borrowers or those with medical history it can add a significant amount to the monthly payment.
The good news is that you are not obliged to take the bank’s own group policy. Borrowers have the right to substitute an alternative insurer at any point during the loan, provided the cover is equivalent. Over a twenty-year term, moving from a bank’s standard group scheme to a competitively sourced individual policy can save a substantial sum — and it is one of the few levers that remains available long after completion.
The bottom line
The French market asks more of you at application and rewards you afterwards. The documentation burden is heavier, the timeline is longer, and the debt-ratio rules are less flexible than a UK buyer will be used to. In exchange you get a rate fixed for the life of the loan, statutory limits on exit costs, and a genuine right to reduce your insurance bill.
Judged over twenty years rather than two, it is a comparison that flatters France.
Talk to BlueSky
BlueSky Finance is an independent broker specialising in French mortgages for UK residents and other international buyers. We know which lenders treat sterling income favourably, how to present a UK financial profile to a French credit committee, and where the negotiating room sits on rates, fees and insurance. Contact our team to discuss your purchase.
How a French Mortgage Can Reduce Your Tax Bill: Wealth Tax & Income Benefits

Most buyers approach a French mortgage as a funding question: how much can I borrow, and at what rate? That is the right first question. It is rarely the most valuable one.
Used deliberately, euro-denominated debt is one of the more effective planning tools available to an international owner of French property. It reduces the base on which France’s wealth tax is charged, it shelters rental income, and it can significantly lower the cost of transferring property to the next generation. None of these effects are loopholes — they are the ordinary consequence of how French tax law treats liabilities.
Here is how each one works.
1. Reducing exposure to IFI wealth tax
France abolished its general wealth tax in 2018 and replaced it with the Impôt sur la Fortune Immobilière, a tax charged specifically on real estate. It bites once net taxable property assets exceed €1.3 million on 1 January. French tax residents are assessed on their worldwide property; non-residents are assessed on their French property alone.
The rates are progressive. Once the threshold is crossed, the charge is calculated from €800,000 upwards — 0.5% to €1.3 million, 0.7% from €1.3 million to €2.57 million, 1% to €5 million, 1.25% to €10 million and 1.5% above that. A partial relief, the décote, softens the cliff edge for estates between €1.3 million and €1.4 million.
The critical word is “net”. Debt taken out to acquire, construct, repair, maintain or improve a taxable property is deducted from that property’s value. A couple holding a €2.5 million French home outright face a meaningful annual charge. The same couple holding the same home with €1.4 million of acquisition debt may sit outside the net altogether in the early years.
Two caveats matter. First, interest-only structures are treated on a degressive basis, with a notional amount of capital deemed repaid each year, so the deduction erodes over time. Second, for larger estates a cap restricts the proportion of debt that can be deducted. Both are reasons to structure the loan with advice rather than assume the benefit.
There is also a valuation point worth knowing: a French main residence attracts an automatic 30% reduction from market value before IFI is calculated.
2. Sheltering rental income
If the property is let, financing costs stop being a cost and start being a deduction.
Under the régime réel, loan interest is deductible from rental income. This applies to unfurnished lettings taxed as revenus fonciers and to furnished lettings under the LMNP regime taxed as bénéfices industriels et commerciaux. The deduction is not limited to interest: arrangement fees, guarantee and mortgage registration costs, release fees and associated bank charges are generally deductible too.
For a non-resident landlord, this is often the difference between a French tax liability and none. A property yielding €30,000 a year with €18,000 of interest and running costs presents a very different picture to the tax office than the same property owned free of debt.
The distinction to keep in mind is that the flat-rate micro regimes offer a fixed allowance instead of actual expenses. Where a property carries real debt, the régime réel is almost always the better election — but the choice has consequences and should be made with an accountant.
One thing France does not offer: interest on a main residence is not deductible against general income. The relief that once existed was withdrawn many years ago and has not returned.
3. Passing property on for less
This is the benefit most buyers have never heard of, and for families it can dwarf the others.
Where a French property is held through a société civile immobilière — an SCI — the asset passed to the next generation is not the building but the shares in the company. And those shares are valued net of the company’s liabilities. In broad terms:
Value of the shares = value of the property − the SCI’s debt
A property worth €1.2 million inside an SCI carrying €700,000 of mortgage debt supports a share valuation in the region of €500,000. Gifts of shares are assessed on that reduced figure, not on the gross property value.
Layer on France’s standard gift allowances — €100,000 per parent, per child, renewable every fifteen years — and a phased transfer becomes considerably more efficient. A couple with two children can move €400,000 of value within a single fifteen-year window before gift tax applies at all. Add the option of gifting bare ownership while retaining a life interest, where the taxable value is discounted according to the donor’s age under the statutory scale, and the planning space widens further.
The important sequencing point: this works best while the debt is still substantial. Waiting until the mortgage is repaid removes the very discount that makes the strategy effective.
A word of caution
Every one of these advantages depends on how the loan and the ownership structure are put together at the outset. An SCI created for the wrong reasons can create problems — particularly for US and UK taxpayers, where the entity may be characterised unhelpfully by their home tax authority. The IFI debt rules contain deliberate anti-avoidance provisions. And the interaction between French relief and the tax you pay at home is governed by treaty, not by convenience.
The tax benefits are real. They are not automatic.
Talk to BlueSky
BlueSky Finance arranges mortgages for expatriates and non-resident buyers across France, and works alongside your notaire, accountant and wealth adviser to make sure the financing supports the wider plan rather than cutting across it. If you would like to understand how a euro mortgage could sit within your tax position, contact our team for an initial conversation.
Why Borrowing in Euros Beats Cash (Even If You Have the Money)

There is a particular kind of buyer we speak to often at BlueSky. They have identified the property. The funds are sitting in a brokerage account, a savings account or a business. And they have already decided that a mortgage would be an unnecessary complication.
It is an understandable instinct. It is also, in most cases, the more expensive decision.
Financing a French property is not simply a way to bridge a shortfall. For internationally mobile buyers, a euro-denominated mortgage functions as a wealth management instrument in its own right — one that touches tax exposure, currency risk and the performance of the assets you already own. Here is why paying cash is rarely the optimal answer.
The cost of borrowing is lower than the cost of selling
The starting point is arithmetic. Fixed rates for international buyers in France currently sit broadly in the 3.5% to 4.5% range depending on residency, loan size and term, with pledged-asset structures achieving sharper pricing still. Rates are fixed for the life of the loan, and the European Central Bank’s deposit rate has settled near 2% with eurozone inflation stabilised around the same level.
Now consider what paying cash actually requires. Liquidating a diversified investment portfolio to buy a Paris Pied à Terre or a villa in provence means surrendering the long-run return on those assets. Where that portfolio has performed above the cost of your French debt, the mortgage is accretive — you keep the compounding and pay a modest, predictable spread for the privilege.
There is a second cost that is easy to overlook. Selling appreciated securities is a taxable event in most jurisdictions. A capital gains bill triggered purely to fund a property purchase is a permanent loss of capital, not a timing difference. Borrowing avoids it entirely.
Currency: buy euros when it suits you, not when the notaire calls
Cash buyers face an uncomfortable reality. The full purchase price must be converted into euros within a narrow window dictated by the transaction timetable, not by the currency market. If sterling or the dollar happens to be weak on completion day, that is simply the rate you get.
A mortgage changes the shape of that exposure entirely. You convert a deposit rather than the whole price, and the balance is repaid in monthly instalments over fifteen, twenty or twenty-five years. That transforms a single, high-stakes conversion into a long series of small ones — and gives you the flexibility to buy euros in advance when the rate is favourable, whether through a specialist FX broker or by building a euro balance over time.
For buyers whose income and wealth sit in dollars or sterling, this alone often justifies the loan.
The wealth tax argument
France levies an annual wealth tax on real estate, the Impôt sur la Fortune Immobilière (IFI), which applies once net taxable French property assets exceed €1.3 million. Non-residents are assessed on their French property only; French tax residents are assessed worldwide.
The word that matters is net. Loans taken out to acquire, build, repair or improve a taxable property are deductible from the value of that property. A €2 million French home owned outright can sit squarely inside the IFI net; the same home purchased with substantial euro financing may fall below the threshold in the early years of the loan, or attract materially less tax.
The rules are precise and there are anti-abuse provisions — notably a degressive treatment of interest-only structures and a cap on deductible debt for larger estates — so this is territory for a qualified adviser rather than a rule of thumb. But the direction of travel is clear: debt reduces the base on which IFI is charged.
Interest that works harder if you let
If the property will generate rental income, financing costs become deductible. Under the régime réel — available for both unfurnished lettings and furnished lettings under the LMNP regime — loan interest, arrangement fees, guarantee costs and bank charges can be set against rental income, reducing the taxable result.
Buyers who are US taxpayers should also review the position with their American accountant. The interaction of French and US rules around qualified residence interest, foreign tax credits and the France–US treaty is genuinely technical, and the outcome varies considerably from one household to another. It is worth the conversation.
Flexibility is built into French consumer law
A common objection is that a mortgage locks you in. In France, it largely does not. Consumer legislation gives borrowers the right to repay early, and any penalty is capped at the lesser of six months’ interest on the sum repaid . In several circumstances — sale following a professional relocation, involuntary loss of employment, or death — no penalty applies at all. Many lenders will waive early repayment fees at the outset if the point is negotiated properly.
In other words, you can borrow now and repay later if your view changes. The optionality costs very little.
The reframe
Paying cash is not wrong. But it should be a decision, not a default. The right question is not “can I afford to buy outright?” — it is “what is the best use of my capital, given where my assets sit, where my income is earned, and what my tax position looks like on both sides of the border?”
For a great many of our clients, the answer involves a euro mortgage.
Talk to BlueSky
BlueSky Finance is an independent mortgage broker specialising in financing for expatriates, non-residents and international buyers in France. We work with a wide panel of French lenders and structure loans around your residency, currency and wider financial position — not around a single bank’s template. If you are weighing cash against finance, we would be glad to model both. Contact our team for an initial, no-obligation discussion.
How Does an EPC (DPE) Rating Impact Mortgage Pricing in France?
Not long ago, a property’s energy rating was a footnote.
Today, it’s a financial lever—one that can directly influence your mortgage rate, borrowing capacity, and even whether financing is approved at all.
For buyers in France, understanding how the EPC (DPE – Diagnostic de Performance Énergétique) impacts mortgage pricing is no longer optional. It’s essential.
EPC Ratings: From Technical Detail to Financial Driver
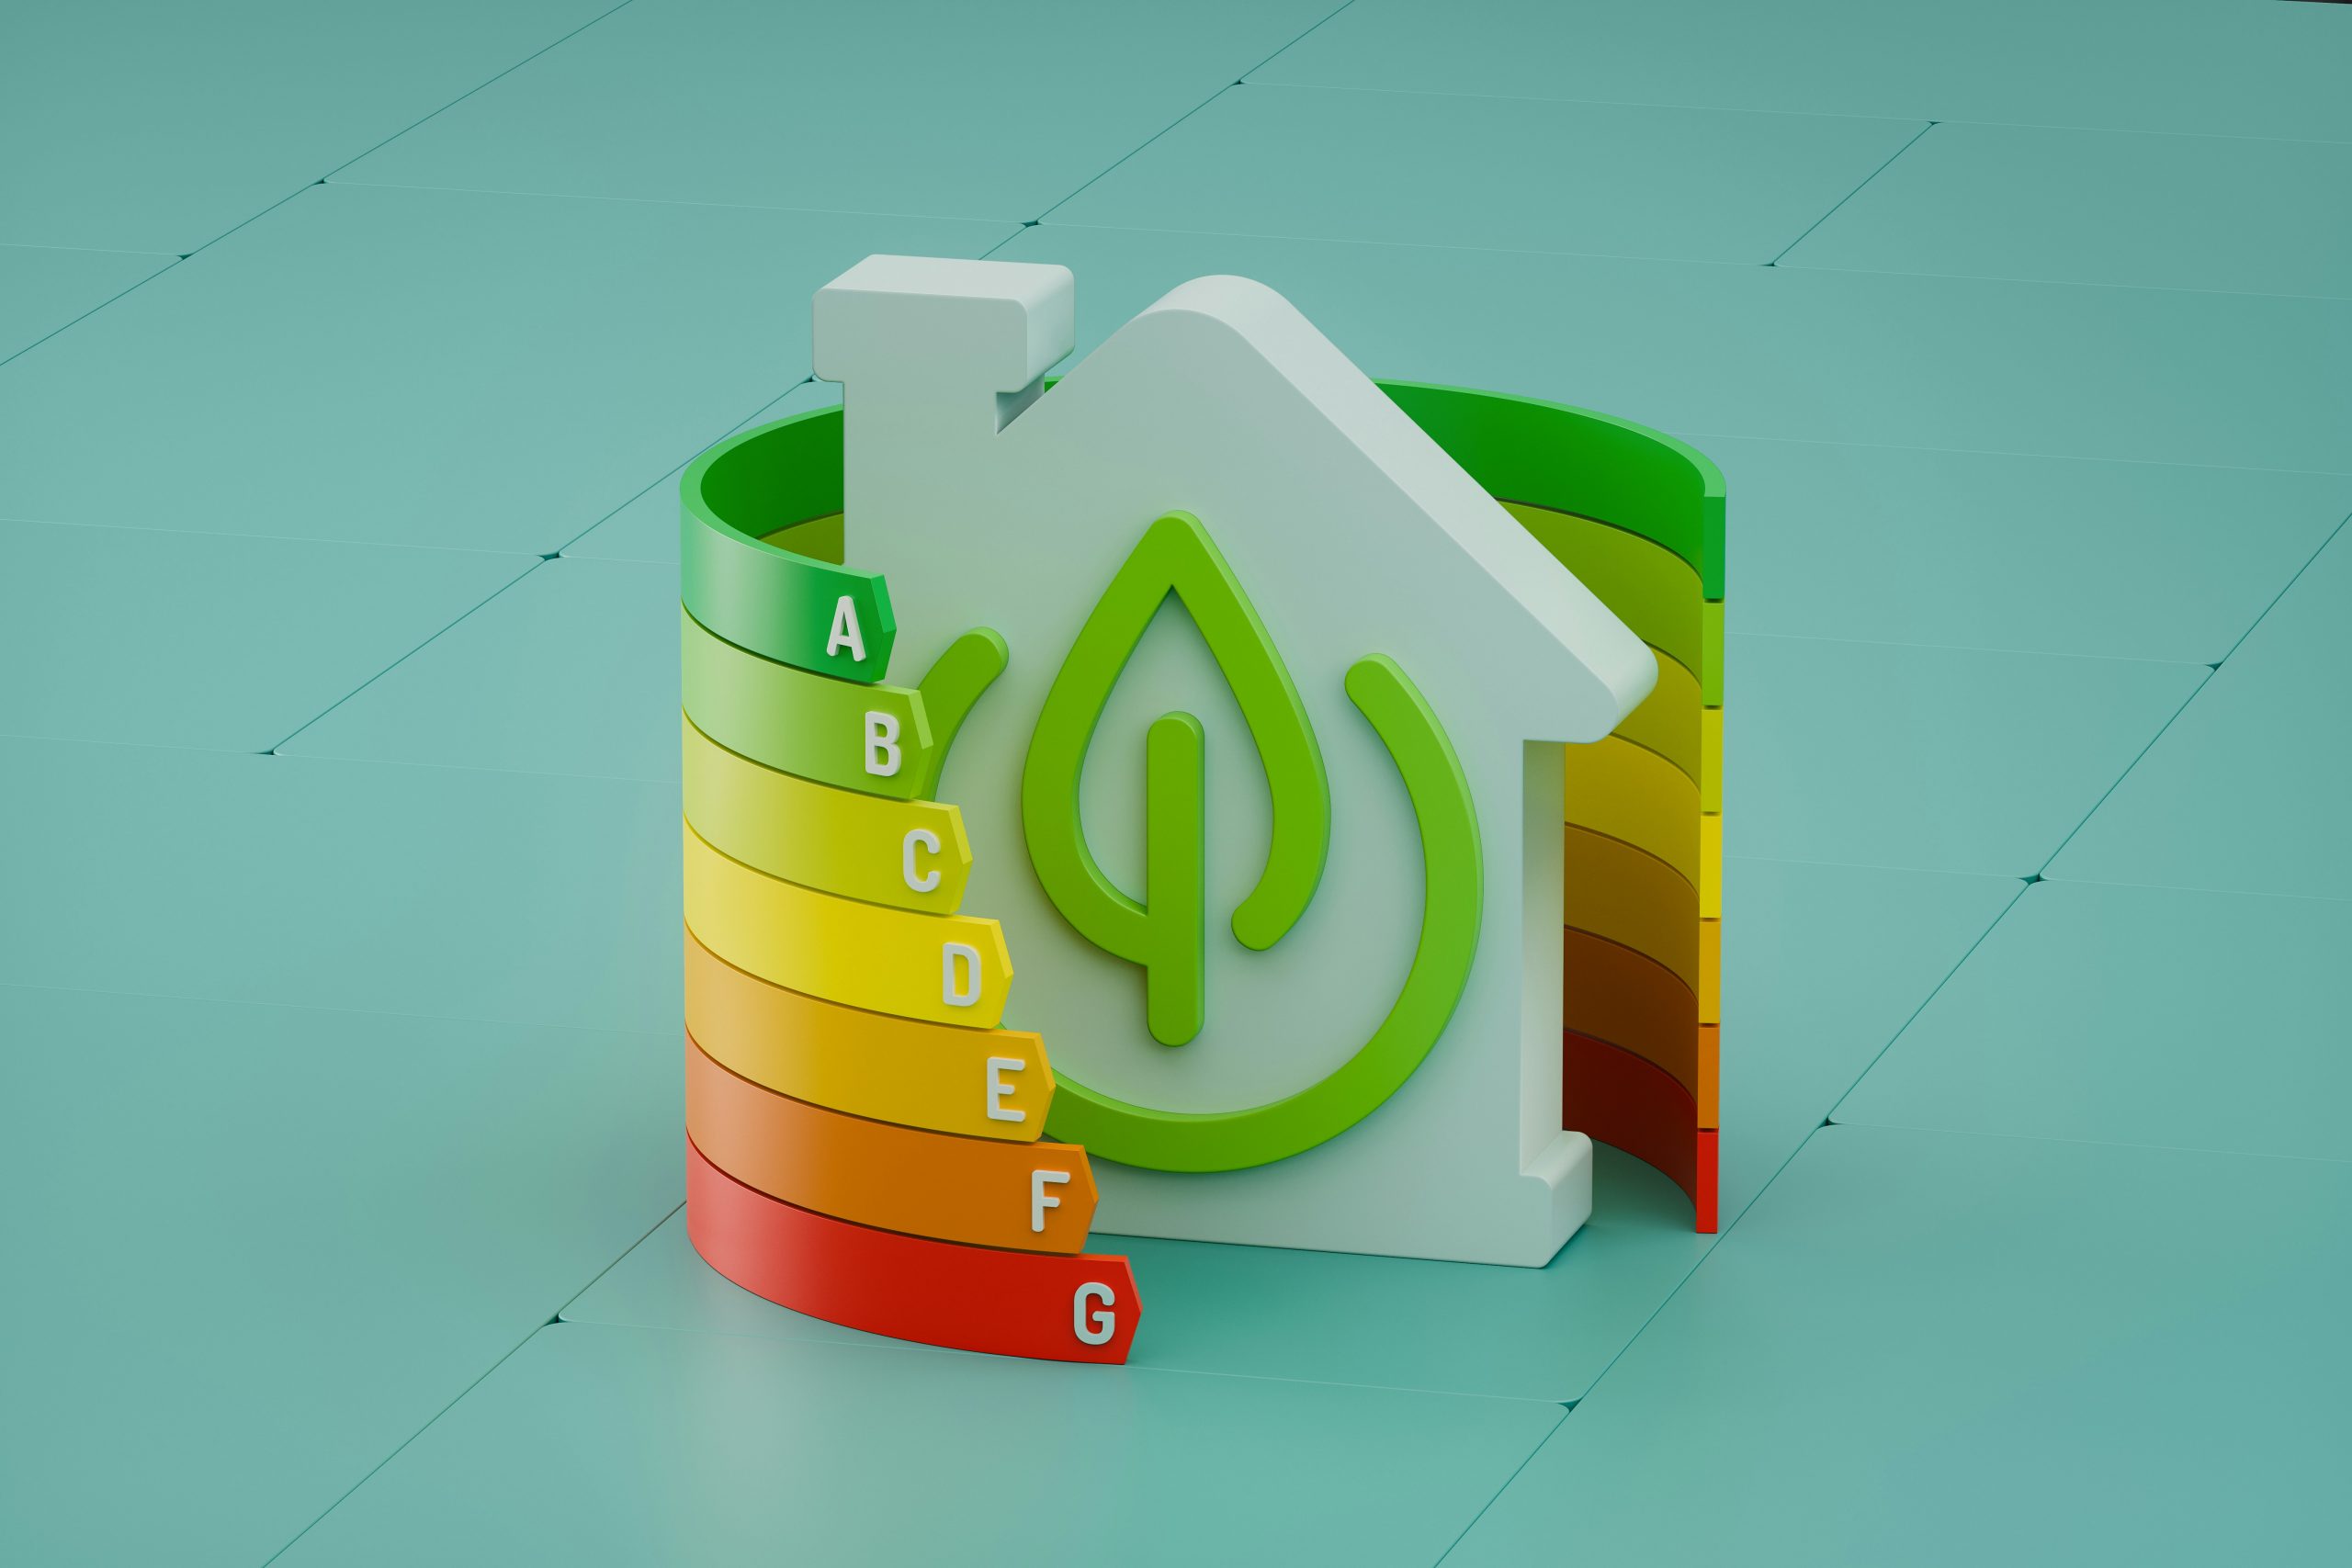
Every property in France is assigned an energy rating from A (most efficient) to G (least efficient).
But this isn’t just about energy bills or environmental impact anymore.
Lenders now treat EPC ratings as a core risk indicator, influencing:
- Interest rates
- Loan-to-value ratios
- Approval conditions
- Future resale and rental viability
In short: energy efficiency has become a credit factor.
Why Lenders Care: Risk, Regulation, and Value
From a lender’s perspective, an inefficient property introduces multiple risks:
1. Regulatory Risk
Properties rated G are already banned from rental as of 2025, with F-rated properties to follow in the coming years
This means:
- Reduced rental income potential
- Lower investor demand
- Increased risk of future illiquidity
2. Value Risk
Energy-inefficient homes often sell at a discount—sometimes significantly.
Buyers factor in:
- Renovation costs
- Future compliance obligations
- Higher running costs
This can affect the long-term value of the lender’s collateral.
3. Financing Risk
Banks are increasingly required to align with sustainability and ESG frameworks, meaning they must actively manage exposure to inefficient housing stock.
As a result, EPC ratings are now embedded directly into underwriting decisions
The Real Impact: How EPC Affects Your Mortgage Pricing
Strong Ratings (A–C): Preferential Treatment
Efficient properties are seen as lower risk and more future-proof.
Borrowers may benefit from:
- More competitive interest rates
- Higher loan-to-value ratios
- Smoother approval processes
Mid Ratings (D–E): Neutral, But Under Review
These properties are still broadly acceptable, but:
- Lenders may apply additional scrutiny
- Future regulation is already tightening (E will be impacted longer term)
Poor Ratings (F–G): Pricing Penalties and Constraints
This is where the impact becomes very tangible.
For F and G-rated properties:
- Higher interest rates are often applied
- Loan amounts may be reduced
- Additional guarantees may be required
- Some lenders may refuse financing altogether
In many cases, buyers must present a clear renovation plan as part of the mortgage application
Rental Restrictions: A Critical Turning Point
The regulatory environment is rapidly tightening.
- G-rated properties: banned from rental (since 2025)
- F-rated properties: restrictions coming from 2028
- Further tightening expected in the years ahead
For lenders, this creates a clear concern:
👉 A property that cannot be rented has reduced income potential and resale appeal
And that directly feeds into pricing and lending decisions.
Can Mortgage Pricing Improve After Renovation?
Yes—and this is where opportunity comes in.
If you are purchasing a lower-rated property with a clear renovation strategy, lenders may:
- Accept the deal based on future value
- Adjust pricing once improvements are completed
- Offer better terms if the EPC rating improves significantly
In some cases, moving from:
- G → E
- F → D
can materially improve financing conditions over time
This creates a powerful strategy:
👉 Buy at a discount → renovate → refinance or reprice
A Strategic Perspective for Buyers
Rather than seeing EPC as a constraint, smart buyers use it as a lever.
- Efficient properties → stability and ease
- Inefficient properties → negotiation power and upside (if managed correctly)
The key is understanding how lenders will view the asset—not just today, but in 5–10 years under evolving regulation.
Final Thoughts: Energy Efficiency is Now Financial Strategy
The shift is clear.
EPC ratings are no longer just environmental indicators—they are core financial metrics shaping:
- Property values
- Rental viability
- Mortgage pricing
And increasingly, they will define which properties are:
- Easy to finance
- Expensive to finance
- Or simply not financeable at all
Considering buying a property in France—especially one requiring renovation?
Understanding how EPC ratings impact your mortgage can save you thousands—and help you structure your purchase more strategically.
At BlueSky Finance, we help international buyers navigate lender requirements, optimise financing, and turn energy challenges into opportunities.
Speak to our team today and make your property investment work smarter.
Prêt Viager Hypothécaire vs Vente en Viager: Two Very Different Ways to Unlock Property Wealth

For many property owners in France—particularly later in life—the question isn’t just what your property is worth, but how you can unlock that value.
Two solutions often come up:
👉 Prêt viager hypothécaire (PVH)
👉 Vente en viager
They are frequently confused.
But in reality, they are fundamentally different—not just in structure, but in risk, control, and long-term impact on your wealth and family.
The Core Difference: Loan vs Sale
At the highest level, the distinction is simple:
- Prêt viager hypothécaire = a loan secured against your property
- Vente en viager = a sale of your property
Everything else flows from this difference.
What is a Prêt Viager Hypothécaire?
A prêt viager hypothécaire allows you to borrow money using your property as collateral—without selling it.
Key Characteristics:
- You remain the full owner of your property
- You receive a lump sum (or sometimes payments)
- There are no monthly repayments during your lifetime
- The loan (capital + interest) is repaid when the property is sold or upon death
In practical terms, it functions like a reverse mortgage.
You unlock liquidity… while keeping control.
What is a Vente en Viager?
A vente en viager is a property sale—but with a unique structure.
Key Characteristics:
- You sell your property immediately
- You typically receive:
- A lump sum upfront (bouquet)
- A lifetime income (rente viagère)
- You may continue living in the property (viager occupé)
- The buyer takes full ownership, but gains possession only upon your death (in most cases)
This is not financing—it is a lifetime income arrangement tied to your property.
Ownership: The Defining Line
This is the most important distinction.
With a Prêt Viager Hypothécaire:
- You keep ownership
- The property remains part of your estate
- Your heirs can choose to keep or sell the property
With a Vente en Viager:
- You transfer ownership immediately
- The property is no longer yours
- It cannot be passed on to heirs
This single difference has profound implications for wealth planning.
Income vs Capital: What Do You Need?
The two structures serve different financial goals:
Prêt Viager Hypothécaire:
- Best for accessing capital
- Ideal for:
- Large one-off needs (renovation, gifting, one-off expenses)
- Maintaining full financial independence
Vente en Viager:
- Best for regular income
- Ideal for:
- Supplementing retirement
- Creating predictable cash flow for life
In short:
👉 PVH = liquidity
👉 Viager = income
Risk and Dependency
Another major difference lies in who carries the risk.
With a Vente en Viager:
- You depend on the buyer to continue paying the rent
- The total amount you receive depends on how long you live
- The transaction is inherently uncertain
With a Prêt Viager Hypothécaire:
- You receive your capital upfront and guaranteed
- No dependency on a third-party buyer
- The structure is financially predictable
This makes the PVH feel more like a controlled financial product, whereas viager is closer to a lifetime agreement with inherent uncertainty.
Flexibility and Control
Prêt Viager Hypothécaire:
- You can sell the property at any time
- You remain free to manage your asset
- You retain full control over your living situation
Vente en Viager:
- The property is no longer yours
- Your rights are defined by the contract (usufruit or usage rights)
- Flexibility is significantly reduced
Which One is Right for You?
There is no one-size-fits-all answer.
It depends on your priorities:
- Want to retain ownership and pass on wealth? → Prêt viager hypothécaire
- Want to maximise lifetime income and reduce estate exposure? → Vente en viager
- Want certainty and independence? → PVH
- Comfortable with a long-term contractual arrangement? → Viager
Final Thoughts: A Strategic Decision, Not Just a Financial One
Choosing between a prêt viager hypothécaire and a vente en viager is not just about money.
It’s about:
- Control vs transfer
- Flexibility vs commitment
- Capital vs income
- Personal freedom vs structured dependency
Both can be powerful tools—but only when aligned with your broader financial and family objectives.
Considering how to unlock the value of your property in France?
The right solution depends on your goals, your timeline, and your long-term financial strategy.
At BlueSky Finance, we help you evaluate all options—clearly, objectively, and with your interests at the centre.
Speak to our team today for expert guidance tailored to your situation.